How to Build Wealth in Austria: A Practical Guide to Saving and Investing
Advertisement
Learn how to build wealth in Austria with practical tips on saving, investing, and managing your money using local banks and financial tools.
Building Wealth in Austria: Where to Start
Austria offers a stable financial environment, a strong social safety net, and a wide range of banking and investment products — yet many residents still struggle to grow their personal wealth beyond a basic savings account. Whether you are just beginning your financial journey or looking to optimize what you already have, understanding the local landscape is the first step toward building lasting financial security.
This guide walks you through the key pillars of wealth-building in Austria: smart saving habits, investment options available locally, and the mindset shifts that separate those who accumulate wealth from those who merely manage expenses.
The Austrian Saving Culture: A Double-Edged Sword
Austrians are traditionally conservative savers. The classic Sparbuch — a passbook savings account — remains one of the most used financial instruments in the country. While this habit of saving is admirable, keeping all your money in a low-yield savings account means your purchasing power slowly erodes over time due to inflation.
The first step to building wealth is recognizing that saving alone is not enough. You need your money to work for you — and that means putting it into instruments that generate real returns over time. The good news is that Austrian residents have access to a growing number of options beyond the traditional Sparbuch.
How Much Should You Save Each Month?
There is no universal answer, but the principle is consistent: save before you spend, not the other way around. Automating a fixed transfer to a savings or investment account on payday removes the temptation to spend first and save what is left. Even modest, consistent contributions compound significantly over years and decades.
As a starting framework, many financial advisors suggest allocating a portion of your net income to savings, another portion to investments, and keeping the rest for living expenses and short-term goals. The exact split depends on your income, obligations, and life stage — what matters most is consistency.
Savings Accounts and Tagesgeld in Austria
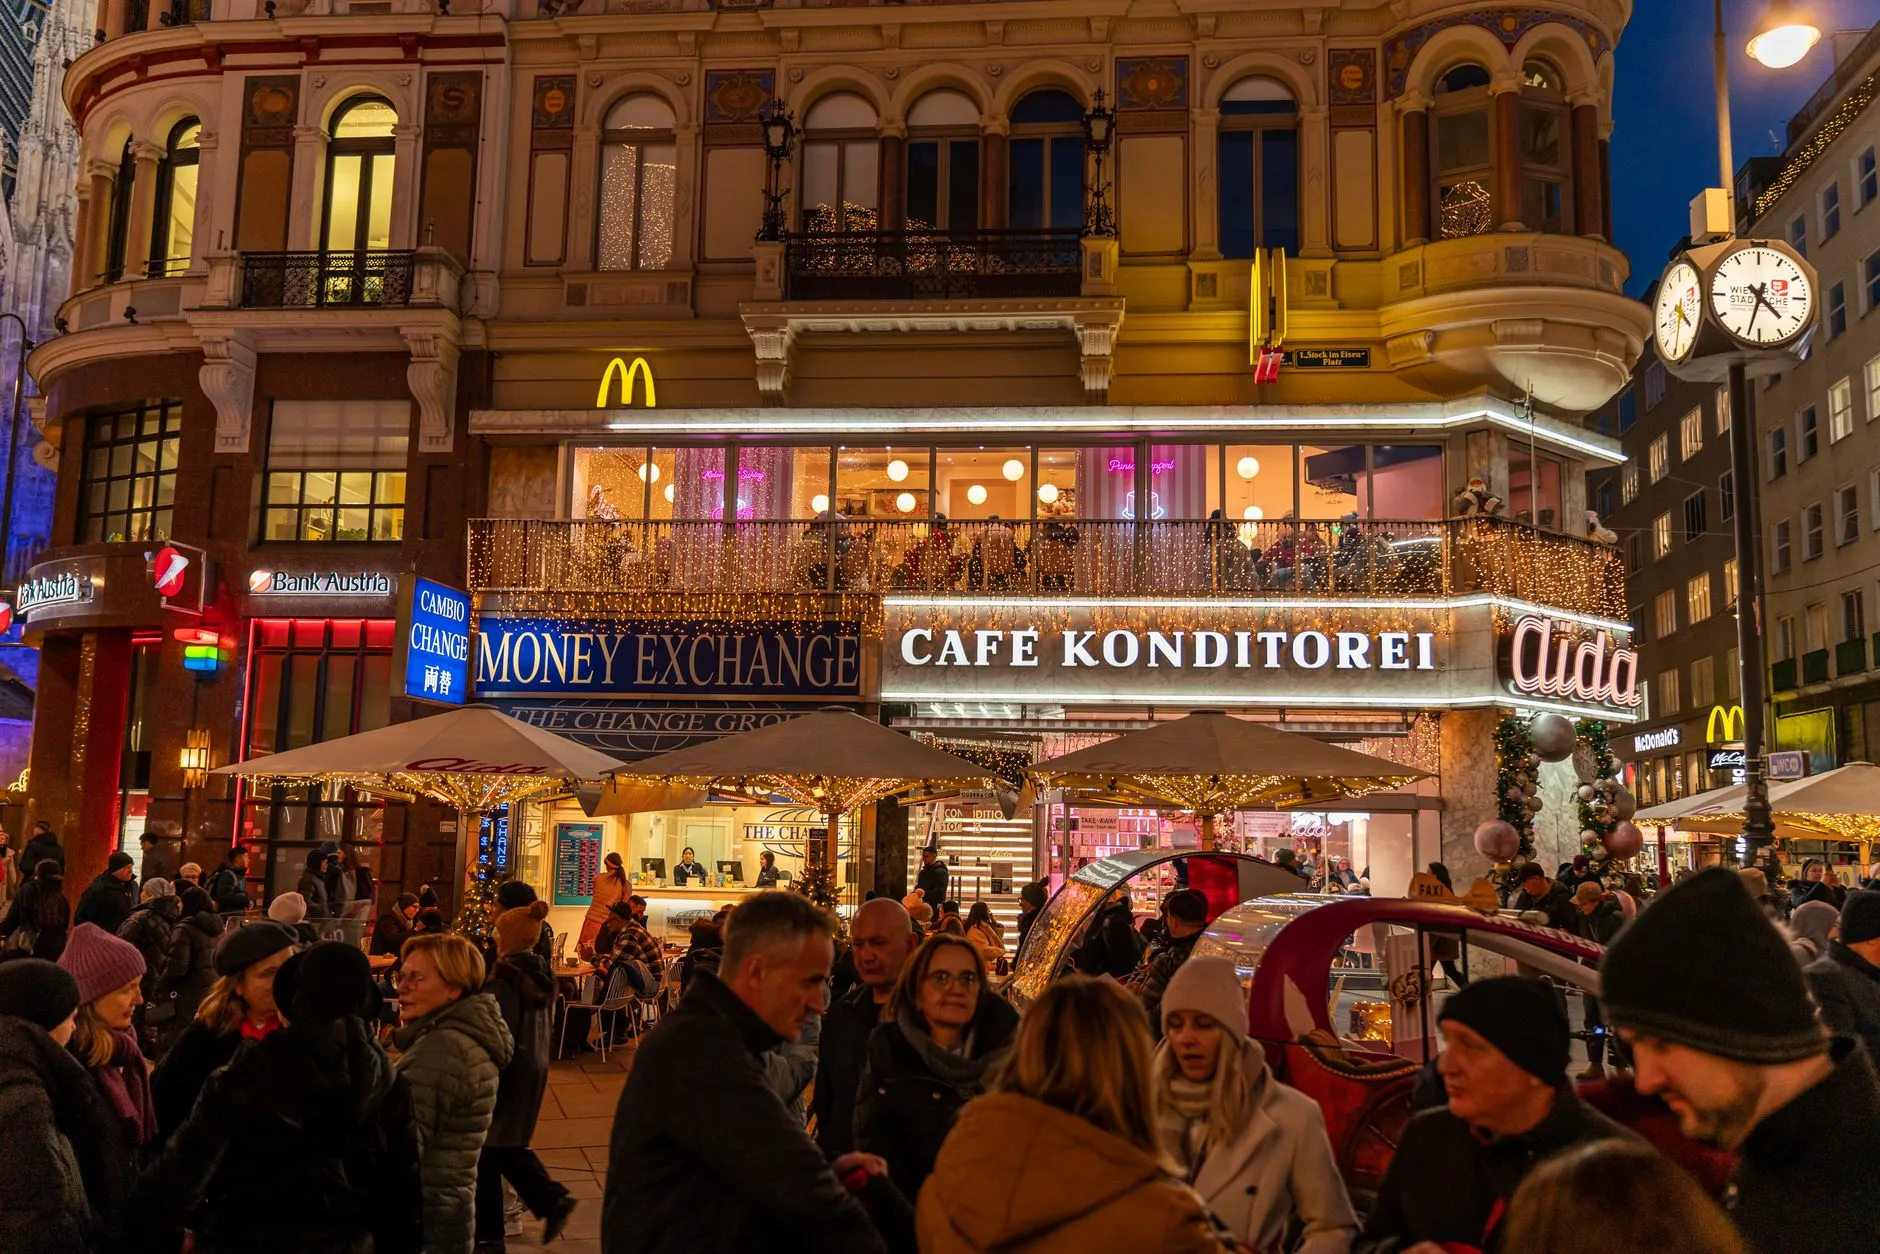
Beyond the Sparbuch, many Austrian banks offer Tagesgeld accounts — overnight or flexible-term deposit accounts that typically offer better interest rates than standard savings books while keeping your funds accessible. Major institutions such as Bawag P.S.K. and Bank Austria offer these products, and rates can vary significantly between providers, so it is worth comparing current offers before committing.
Fixed-term deposits (Festgeld) are another option for money you do not need immediate access to. These lock your funds for a set period in exchange for a higher rate. Always check the current rate and conditions directly with the bank, as these figures change frequently.
Using Raiffeisen and Volksbank Networks for Savings
Austria's cooperative banking network — including Raiffeisen and Volksbank branches — often provides competitive savings products alongside a relationship-banking approach. Regional branches may offer localized products or promotional rates, so speaking directly with an advisor at your nearest branch can uncover options not always visible online.
Investing in Austria: Moving Beyond the Savings Account
Once you have an emergency fund in place — typically covering several months of essential living expenses — the next step is putting additional capital to work through investments. Austria offers several accessible routes for retail investors.
Investment Funds (Investmentfonds)
Austrian banks and independent brokers offer access to a wide range of mutual funds and ETFs (exchange-traded funds). These allow you to invest in diversified portfolios of stocks, bonds, or mixed assets without needing to pick individual securities. Many Austrian banks, including those within the Raiffeisen group, have their own fund management arms with domestically registered products.
ETFs in particular have gained popularity among cost-conscious investors due to their typically lower ongoing fees compared to actively managed funds. That said, all investments carry risk, and past performance does not guarantee future results. Consult a licensed financial advisor before making investment decisions.
The Austrian Securities Account (Wertpapierdepot)
To invest in stocks, ETFs, or bonds, you will need a securities account, known locally as a Wertpapierdepot. Most Austrian banks offer these, and there are also online brokers operating in Austria that may offer lower transaction costs. Compare custody fees, trading commissions, and the range of available instruments before opening an account.
Real Estate as a Wealth-Building Tool
Property ownership has historically been viewed as one of the most reliable wealth-building strategies in Austria. However, purchasing real estate requires significant capital, involves transaction costs, and comes with ongoing responsibilities. Rental income can supplement your cash flow, but managing tenants and property is not passive. If property investment interests you, seek independent legal and tax advice specific to Austrian real estate law before proceeding.
Tax Considerations for Austrian Investors
Austria levies a capital gains tax (Kapitalertragsteuer, or KESt) on investment income including dividends and realized gains. The tax is generally withheld automatically by Austrian financial institutions, which simplifies the process for most retail investors. However, the rules can become more complex if you invest through foreign brokers or hold certain types of instruments.
It is strongly advisable to consult a tax professional (Steuerberater) familiar with Austrian investment taxation, especially as your portfolio grows or if you receive income from multiple sources.
Zukunftsvorsorge: Austria's State-Supported Pension Savings
Austria's Prämienbegünstigte Zukunftsvorsorge is a state-subsidized savings and investment product designed to encourage long-term retirement saving. It comes with an annual government premium and favorable tax treatment, but also has restrictions on how and when you can access the funds. Check with your bank or an independent advisor for the current premium rate and eligibility conditions, as these are reviewed periodically by the government.
Building Good Financial Habits in Austria
Technical knowledge about savings accounts and investment vehicles is important, but sustainable wealth-building rests equally on behavior and discipline. A few habits that make a consistent difference:
- Track your spending: You cannot manage what you do not measure. Use a budgeting app or a simple spreadsheet to categorize your monthly outflows and identify where your money actually goes.
- Eliminate high-cost debt first: Before aggressively investing, pay down any expensive credit or consumer loans. Interest paid on debt typically outweighs investment returns in the short term.
- Avoid lifestyle inflation: As your income grows, resist the urge to proportionally increase your spending. Directing income raises toward savings and investments accelerates your progress dramatically.
- Review your finances regularly: Set a recurring time — monthly or quarterly — to review your accounts, rebalance investments if needed, and adjust your plan as your circumstances change.
When to Seek Professional Advice
Building wealth is not a one-size-fits-all process. Life events such as marriage, children, inheritance, career changes, or approaching retirement all create moments where professional guidance adds real value. In Austria, you can work with a certified financial planner, a bank advisor, or an independent Finanzberater. Always verify the credentials and any potential conflicts of interest of anyone advising you on financial products.
If you are exploring the broader banking landscape to find the right home for your savings, it can help to read detailed reviews of Austrian institutions. For example, understanding how regional cooperative banks like Volksbank structure their savings and advisory services can help you make a more informed choice.
Final Thoughts
Building wealth in Austria is achievable with patience, consistency, and the right combination of savings discipline and smart investing. The infrastructure is in place — from solid cooperative banks to state-supported retirement products and a growing range of investment platforms. What separates those who build wealth from those who do not is rarely access to secret information; it is the willingness to start, stay consistent, and adjust over time. Begin with what you have today, and let compounding do the rest.
Lauren Hartwell
Brooklyn-based money management columnist covering budgeting, saving, and everyday financial habits.